 by
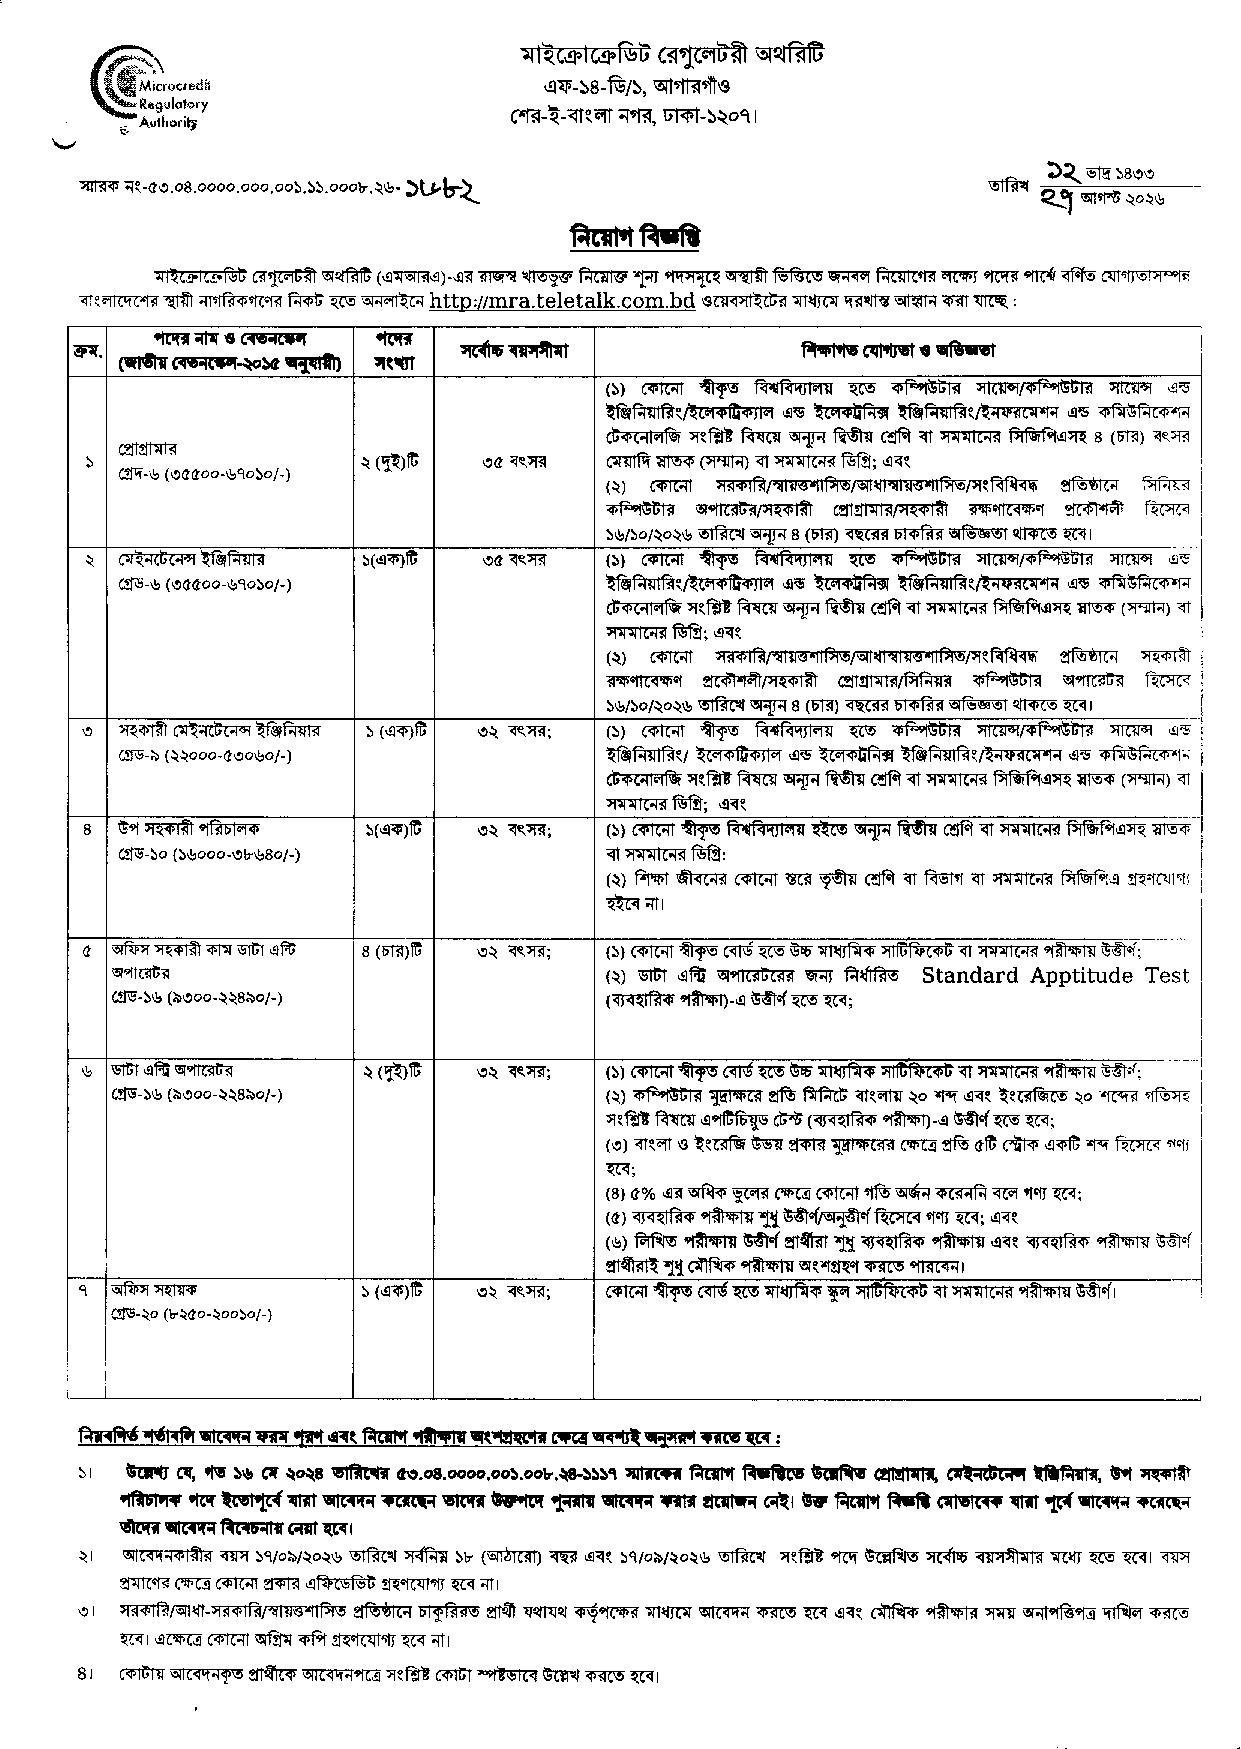
Name : Microcredit Regulatory Authority (NRA)
Website : https://mra.gov.bd
Facebook Page
Wikipedia
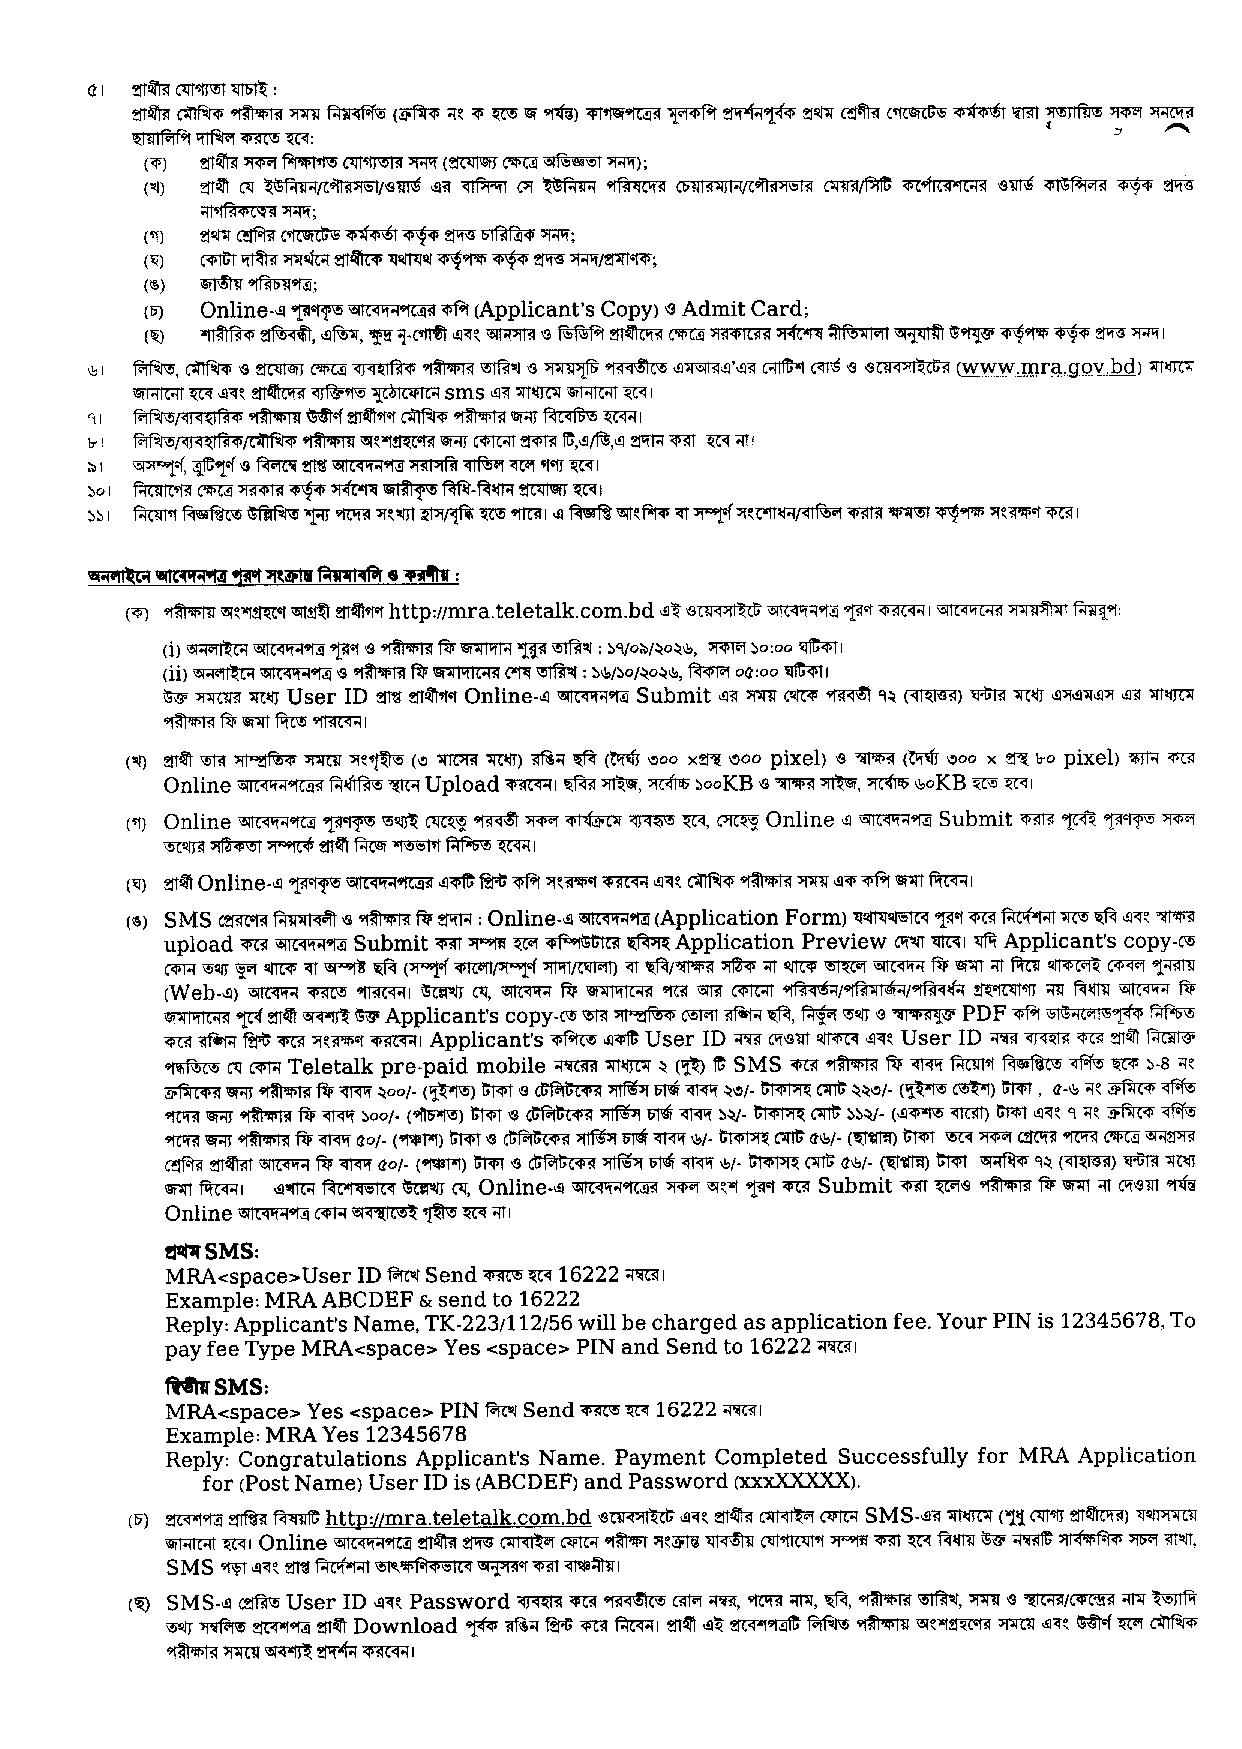
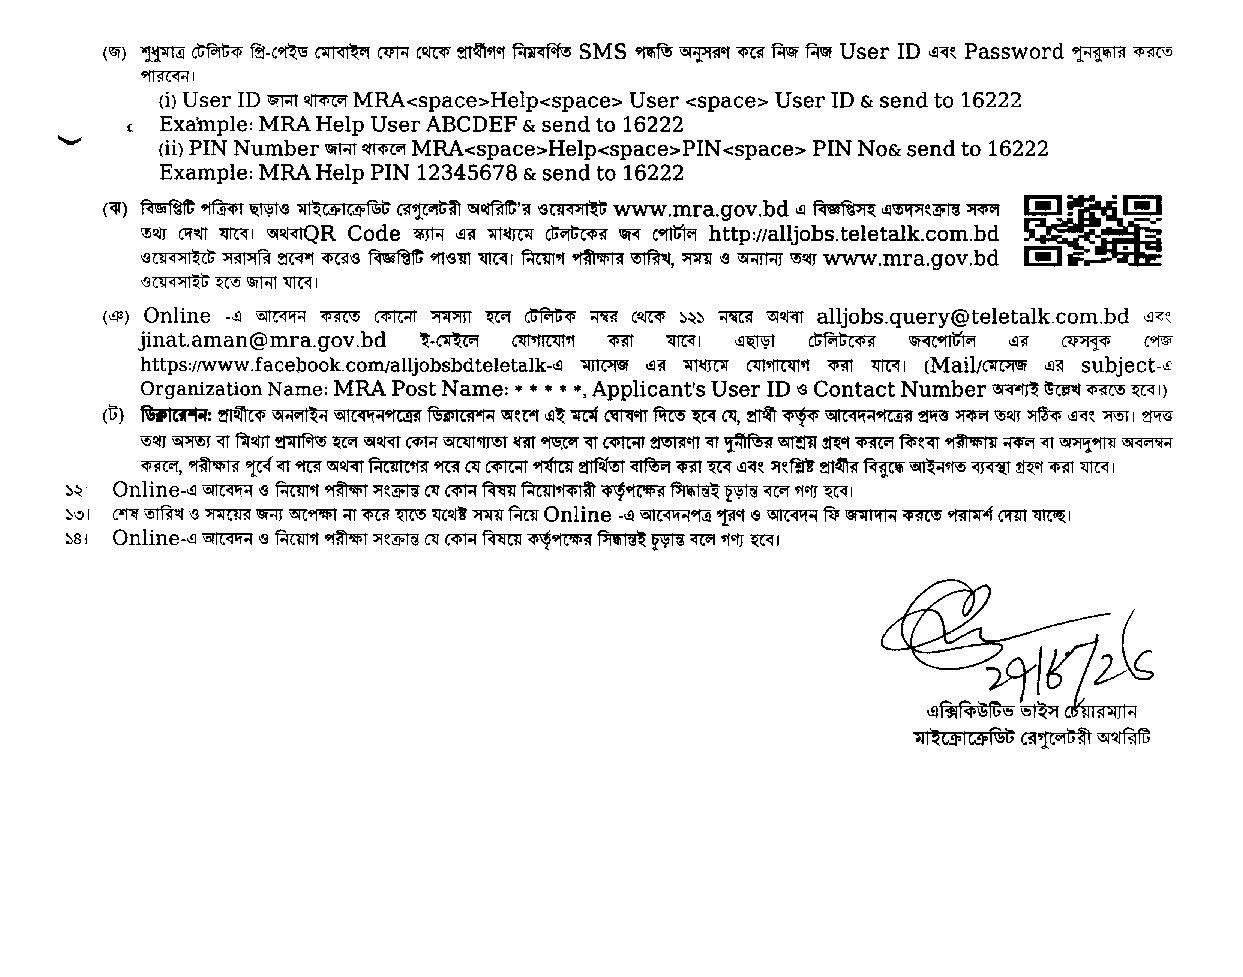
Online Apply https://mra.teletalk.com.bd
Source: Online
Date of the Circular: 27/08/2026
Last Date of Application: 16/10/2026
Total Post : 13
Microcredit Regulatory Authority (MRA) Bangladesh: Functions, Law, Licensed MFIs and Important Information
The Microcredit Regulatory Authority (MRA) is an important regulatory institution for Bangladesh’s microfinance sector. It was established to bring private microcredit organizations under an appropriate regulatory framework and to promote transparency and accountability in the microcredit sector.
Microfinance has an important place in Bangladesh’s financial and socioeconomic landscape. Many low-income households, small entrepreneurs and rural communities use microcredit services for different economic activities. A regulatory framework is therefore important for maintaining discipline, transparency and accountability within the sector.
What Does MRA Stand For?
MRA stands for Microcredit Regulatory Authority.
In Bangla, the organization is known as মাইক্রোক্রেডিট রেগুলেটরী অথরিটি.
It is worth noting that “NRA” is sometimes incorrectly used online. The correct abbreviation of Bangladesh’s Microcredit Regulatory Authority is MRA.
When Was the Microcredit Regulatory Authority Established?
The Government of Bangladesh introduced the Microcredit Regulatory Authority Act, 2006, to bring private microcredit organizations under a regulatory framework.
The Act is identified as Act No. 32 of 2006. According to the official MRA website, the law came into effect on 27 August 2006, and the Microcredit Regulatory Authority was established to implement its objectives.
The legislation created an institutional framework for regulating and monitoring the private microfinance sector.
Main Objectives of MRA
The broad objectives of the Microcredit Regulatory Authority include maintaining a regulatory framework for the microcredit sector and supporting transparency and accountability.
Its important areas of responsibility include:
- Regulating relevant microcredit organizations
- Supporting transparency in the microfinance sector
- Promoting accountability
- Maintaining information on licensed microfinance organizations
- Collecting and publishing microfinance-related information
- Implementing relevant laws, regulations and guidelines
- Supporting a more organized microcredit sector
MRA Law and Regulations
The principal legal foundation of MRA is the Microcredit Regulatory Authority Act, 2006. The official MRA website also publishes relevant regulations, rules and guidelines.
The Microcredit Regulatory Authority Rules, 2010 (Amendment 2022) is one of the regulatory documents listed on the official website.
The authority also publishes the Microcredit Information Rules, 2020, which relates to information management in the microcredit sector.
Why Is MRA Important?
Bangladesh has a large microfinance sector involving numerous organizations and millions of financial transactions. A regulatory institution is therefore important for maintaining an organized framework.
MRA provides regulatory oversight and publishes information and statistics about the sector. One important source is its Microfinance in Bangladesh (Annual Statistics) series. The official website lists the 2024 edition among its publications.
Such publications are useful for researchers, students, policymakers, journalists and people interested in Bangladesh’s microfinance sector.
What Are Licensed Microfinance Organizations?
The status of a microfinance organization is an important consideration for people using microcredit services.
MRA publishes lists of licensed microfinance organizations through its official website. The authority also maintains information concerning organizations whose licenses have been cancelled.
Because institutional status can change over time, anyone checking an organization should rely on the latest official MRA list rather than an old article, social-media post or unofficial directory.
Major Functions of MRA
1. Regulation of Microfinance Organizations
MRA plays a regulatory role in maintaining the framework within which relevant private microcredit organizations operate.
2. Licensing and Institutional Information
The authority publishes information on licensed microfinance organizations and, where applicable, organizations whose licenses have been cancelled. This allows stakeholders to verify institutional status through official information.
3. Microfinance Statistics
MRA publishes statistical information about Bangladesh’s microfinance sector. Its official publication list includes Microfinance in Bangladesh (Annual Statistics), 2024.
4. Annual Reports
MRA publishes annual reports describing its activities and institutional performance. The official website lists the Annual Report 2024, published on 30 March 2025, along with reports from earlier years.
5. Implementation of Regulatory Frameworks
The authority has an important role in applying the relevant legal, regulatory and guideline framework governing the microcredit sector.
MRA Annual Reports
Annual reports are useful sources for understanding the activities of a regulatory organization.
MRA’s official website provides annual reports for multiple years, including the 2024 annual report. These documents can be useful for researchers, students, journalists, microfinance professionals and others interested in the sector.
Readers should use the latest available report when researching current developments.
Microfinance Statistics in Bangladesh
MRA’s annual statistical publications provide useful information about the country’s microfinance sector.
The official MRA website lists Microfinance in Bangladesh (Annual Statistics), 2024, published in January 2025.
These publications can help readers understand the scale and development of microfinance activities in Bangladesh.
Important Tips for Microcredit Borrowers
Before taking a microcredit loan, borrowers should carefully examine the terms and conditions rather than looking only at the amount of the loan or the size of the installment.
Important points to check may include:
- Whether the organization appears on the latest MRA licensed list
- Loan amount
- Number of installments
- Repayment schedule
- Applicable service charges or other lawful costs
- Total amount payable
- Terms and conditions
- Customer support and complaint procedures
Loan terms can vary between organizations and may change over time. Therefore, borrowers should check the latest documents provided by the relevant organization and consult official MRA information when appropriate.
MRA Jobs and Career Opportunities
MRA may also be of interest to people looking for government-sector employment opportunities.
Recruitment notices can be issued for different positions from time to time. However, the number of vacancies, educational qualifications, age requirements, application fees, deadlines and application procedures may change from one recruitment circular to another.
Applicants should therefore verify the latest official MRA job circular before submitting an application.
Old recruitment notices should not be presented as current job opportunities.
What Information Is Available on the MRA Website?
The official MRA website provides different categories of information, including:
- Laws
- Regulations
- Rules and guidelines
- Annual reports
- Microfinance statistics
- Lists of licensed microfinance organizations
- Information on cancelled licenses
- Institutional reports
- Annual performance-related documents
- Notices and official publications
Since government websites and regulatory information can be updated, readers should check the latest publication before making an important financial or professional decision.
Frequently Asked Questions About MRA
What is the full form of MRA?
MRA stands for Microcredit Regulatory Authority.
What is MRA in Bangladesh?
MRA is the regulatory authority responsible for the regulatory framework of the private microcredit sector in Bangladesh. It was established under the Microcredit Regulatory Authority Act, 2006.
What is the MRA Act?
The main legislation is the Microcredit Regulatory Authority Act, 2006, identified as Act No. 32 of 2006.
Why was MRA established?
MRA was established to bring private microcredit organizations under a regulatory framework and to promote transparency and accountability in the microcredit sector.
How can I check whether a microfinance organization is licensed?
You can check the latest licensed microfinance organization list published by MRA on its official website.
Does MRA publish annual reports?
Yes. MRA publishes annual reports, including the 2024 annual report listed on its official website.
Conclusion
The Microcredit Regulatory Authority (MRA) is an important regulatory institution in Bangladesh’s microfinance sector. Established under the Microcredit Regulatory Authority Act, 2006, it plays a significant role in the regulatory framework, institutional information, statistics, reporting and related oversight of the private microcredit sector.
For microcredit borrowers, microfinance organizations, researchers, students, journalists and job seekers, the official MRA website can be an important source of reliable information.
Before making a financial decision, applying for a job or relying on the status of a microfinance organization, readers should always verify the latest information from official MRA publications.
মাইক্রোক্রেডিট রেগুলেটরী অথরিটি (MRA): ইতিহাস, কার্যাবলি, ক্ষুদ্রঋণ প্রতিষ্ঠান ও গুরুত্বপূর্ণ তথ্য
মাইক্রোক্রেডিট রেগুলেটরী অথরিটি (Microcredit Regulatory Authority – MRA) বাংলাদেশের ক্ষুদ্রঋণ খাতের একটি গুরুত্বপূর্ণ নিয়ন্ত্রক সংস্থা। দেশের বেসরকারি ক্ষুদ্রঋণ প্রতিষ্ঠানগুলোকে একটি নির্দিষ্ট নিয়ন্ত্রণ কাঠামোর আওতায় আনা, স্বচ্ছতা ও জবাবদিহিতা নিশ্চিত করা এবং ক্ষুদ্রঋণ কার্যক্রমের ওপর নিয়ন্ত্রক নজরদারি প্রতিষ্ঠা করা MRA-এর গুরুত্বপূর্ণ দায়িত্বের মধ্যে পড়ে।
বাংলাদেশে ক্ষুদ্রঋণ দীর্ঘদিন ধরে নিম্নআয়ের মানুষ, ক্ষুদ্র উদ্যোক্তা ও প্রান্তিক জনগোষ্ঠীর আর্থিক কার্যক্রমের সঙ্গে যুক্ত। এই খাতে সুশৃঙ্খলা, নিয়মনীতি ও গ্রাহকস্বার্থ রক্ষার প্রয়োজন থেকেই MRA-এর মতো নিয়ন্ত্রক প্রতিষ্ঠানের গুরুত্ব তৈরি হয়েছে।
MRA-এর পূর্ণরূপ কী?
MRA-এর পূর্ণরূপ হলো Microcredit Regulatory Authority। বাংলায় এর নাম মাইক্রোক্রেডিট রেগুলেটরী অথরিটি।
অনেক সময় অনলাইনে ভুলভাবে “NRA” লেখা হলেও বাংলাদেশের ক্ষুদ্রঋণ খাতের নিয়ন্ত্রক সংস্থার সঠিক সংক্ষিপ্ত নাম হলো MRA।
মাইক্রোক্রেডিট রেগুলেটরী অথরিটি কবে প্রতিষ্ঠিত হয়?
বাংলাদেশ সরকার ক্ষুদ্রঋণ খাতকে নিয়ন্ত্রণ কাঠামোর মধ্যে আনার উদ্দেশ্যে মাইক্রোক্রেডিট রেগুলেটরী অথরিটি আইন, ২০০৬ প্রণয়ন করে। এটি ২০০৬ সালের ৩২ নম্বর আইন। MRA-এর সরকারি তথ্য অনুযায়ী, আইনটি ২৭ আগস্ট ২০০৬ থেকে কার্যকর হয় এবং এই আইনের উদ্দেশ্য বাস্তবায়নের জন্য মাইক্রোক্রেডিট রেগুলেটরী অথরিটি প্রতিষ্ঠা করা হয়।
এই আইন ক্ষুদ্রঋণ খাতে নিয়ন্ত্রণ, স্বচ্ছতা ও জবাবদিহিতার জন্য একটি প্রাতিষ্ঠানিক কাঠামো তৈরি করে।
MRA-এর প্রধান উদ্দেশ্য
মাইক্রোক্রেডিট রেগুলেটরী অথরিটির কার্যক্রমের অন্যতম উদ্দেশ্য হলো বেসরকারি ক্ষুদ্রঋণ প্রতিষ্ঠানগুলোকে নিয়ন্ত্রিত কাঠামোর মধ্যে পরিচালনা করা।
প্রধান উদ্দেশ্যগুলোর মধ্যে রয়েছে:
- ক্ষুদ্রঋণ খাতে নিয়ন্ত্রক কাঠামো বজায় রাখা
- ক্ষুদ্রঋণ প্রতিষ্ঠানের কার্যক্রমে স্বচ্ছতা বাড়ানো
- জবাবদিহিতা নিশ্চিত করতে সহায়তা করা
- অনুমোদিত/সনদপ্রাপ্ত ক্ষুদ্রঋণ প্রতিষ্ঠানের কার্যক্রম তদারকি করা
- ক্ষুদ্রঋণ খাতের তথ্য সংগ্রহ ও প্রকাশ করা
- প্রযোজ্য আইন, বিধিমালা ও নির্দেশিকা বাস্তবায়নে ভূমিকা রাখা
- ক্ষুদ্রঋণ খাতকে আরও সুশৃঙ্খলভাবে পরিচালনায় সহায়তা করা
MRA-এর আইন ও বিধিমালা
MRA-এর কার্যক্রমের মূল আইনি ভিত্তি হলো মাইক্রোক্রেডিট রেগুলেটরী অথরিটি আইন, ২০০৬। MRA-এর সরকারি ওয়েবসাইটে এই আইন ছাড়াও বিভিন্ন বিধিমালা, প্রবিধান ও নির্দেশিকা প্রকাশ করা হয়।
এর মধ্যে মাইক্রোক্রেডিট রেগুলেটরী অথরিটি বিধিমালা, ২০১০ (সংশোধন-২০২২) একটি গুরুত্বপূর্ণ বিধিমালা হিসেবে সরকারি সাইটে তালিকাভুক্ত রয়েছে।
এছাড়া ক্ষুদ্রঋণ-সংক্রান্ত তথ্য ব্যবস্থাপনার জন্য ক্ষুদ্রঋণ তথ্য বিধিমালা, ২০২০-ও MRA-এর সরকারি সাইটে প্রকাশিত হয়েছে।
MRA কেন গুরুত্বপূর্ণ?
বাংলাদেশে বিভিন্ন বেসরকারি প্রতিষ্ঠান ক্ষুদ্রঋণ কার্যক্রম পরিচালনা করে। এই খাতে বিপুল সংখ্যক গ্রাহক ও অর্থনৈতিক লেনদেন জড়িত থাকায় একটি নিয়ন্ত্রক কাঠামো গুরুত্বপূর্ণ।
MRA-এর মাধ্যমে ক্ষুদ্রঋণ খাত সম্পর্কে প্রাতিষ্ঠানিক তথ্য সংরক্ষণ, প্রকাশ ও নিয়ন্ত্রণের ব্যবস্থা গড়ে উঠেছে। MRA নিয়মিত বিভিন্ন প্রতিবেদন ও পরিসংখ্যান প্রকাশ করে, যার মধ্যে Microfinance in Bangladesh (Annual Statistics) সিরিজ রয়েছে। সরকারি সাইটে ২০২৪ সালের Annual Statistics-ও তালিকাভুক্ত আছে।
সনদপ্রাপ্ত ক্ষুদ্রঋণ প্রতিষ্ঠান কী?
ক্ষুদ্রঋণ কার্যক্রমের ক্ষেত্রে MRA-এর সনদপ্রাপ্ত প্রতিষ্ঠানগুলোর বিষয়টি অত্যন্ত গুরুত্বপূর্ণ। MRA-এর সরকারি ওয়েবসাইটে সনদপ্রাপ্ত ক্ষুদ্রঋণ প্রতিষ্ঠানসমূহের তালিকা প্রকাশ করা হয়।
বর্তমান তালিকা যাচাই করার ক্ষেত্রে MRA-এর সর্বশেষ প্রকাশিত তালিকাই অনুসরণ করা উচিত, কারণ প্রতিষ্ঠানের সনদ, অনুমোদন বা অবস্থার পরিবর্তন হতে পারে। MRA-এর ওয়েবসাইটে ৩০ জুন ২০২৫ পর্যন্ত সনদপ্রাপ্ত প্রতিষ্ঠানগুলোর তালিকার একটি প্রকাশনাও রয়েছে।
কোনো ক্ষুদ্রঋণ প্রতিষ্ঠানের সঙ্গে আর্থিক লেনদেন করার আগে সংশ্লিষ্ট প্রতিষ্ঠান MRA-এর সর্বশেষ সনদপ্রাপ্ত তালিকায় আছে কি না যাচাই করা একটি গুরুত্বপূর্ণ সতর্কতা।
MRA-এর প্রধান কার্যাবলি
MRA-এর কার্যাবলি বিভিন্ন দিক থেকে ক্ষুদ্রঋণ খাতের সঙ্গে সম্পর্কিত। এর মধ্যে রয়েছে:
১. ক্ষুদ্রঋণ প্রতিষ্ঠান নিয়ন্ত্রণ
ক্ষুদ্রঋণ কার্যক্রম পরিচালনাকারী সংশ্লিষ্ট প্রতিষ্ঠানগুলোকে নির্ধারিত কাঠামোর মধ্যে রাখার ক্ষেত্রে MRA গুরুত্বপূর্ণ ভূমিকা পালন করে।
২. সনদ ও প্রতিষ্ঠান সংক্রান্ত কার্যক্রম
MRA-এর ওয়েবসাইটে সনদপ্রাপ্ত এবং সনদ বাতিল হওয়া ক্ষুদ্রঋণ প্রতিষ্ঠানের তথ্য প্রকাশ করা হয়। এতে সাধারণ মানুষ ও সংশ্লিষ্ট পক্ষগুলো প্রতিষ্ঠানের অবস্থা সম্পর্কে তথ্য যাচাই করার সুযোগ পায়।
৩. তথ্য ও পরিসংখ্যান প্রকাশ
বাংলাদেশের ক্ষুদ্রঋণ খাতের বিভিন্ন তথ্য ও পরিসংখ্যান MRA প্রকাশ করে। Annual Statistics সিরিজের মাধ্যমে খাতটির বিভিন্ন দিক সম্পর্কে তথ্য পাওয়া যায়।
৪. প্রতিবেদন প্রকাশ
MRA নিয়মিত বার্ষিক প্রতিবেদন প্রকাশ করে। সরকারি ওয়েবসাইটে ২০২৪ সালের বার্ষিক প্রতিবেদন ৩০ মার্চ ২০২৫ তারিখে প্রকাশিত হয়েছে বলে উল্লেখ রয়েছে।
৫. আইন ও নির্দেশিকা বাস্তবায়নে ভূমিকা
ক্ষুদ্রঋণ খাতের জন্য প্রযোজ্য আইন, বিধিমালা ও নির্দেশিকার ভিত্তিতে নিয়ন্ত্রণমূলক কার্যক্রম পরিচালনা করা MRA-এর গুরুত্বপূর্ণ দায়িত্ব।
MRA-এর বার্ষিক প্রতিবেদন
কোনো সরকারি বা নিয়ন্ত্রক প্রতিষ্ঠানের কাজ বোঝার জন্য বার্ষিক প্রতিবেদন গুরুত্বপূর্ণ উৎস। MRA-এর ওয়েবসাইটে বিভিন্ন বছরের বার্ষিক প্রতিবেদন প্রকাশ করা হয়েছে। সর্বশেষ তালিকায় ২০২৪ সালের বার্ষিক প্রতিবেদনসহ পূর্ববর্তী বছরগুলোর প্রতিবেদনও রয়েছে।
গবেষক, শিক্ষার্থী, সাংবাদিক, ক্ষুদ্রঋণ খাতের সঙ্গে যুক্ত ব্যক্তি এবং সাধারণ পাঠক এসব প্রতিবেদন থেকে বাংলাদেশের মাইক্রোফাইন্যান্স খাত সম্পর্কে তথ্য পেতে পারেন।
MRA-এর ক্ষুদ্রঋণ পরিসংখ্যান
বাংলাদেশের ক্ষুদ্রঋণ খাত সম্পর্কে তথ্য জানতে MRA-এর Annual Statistics একটি গুরুত্বপূর্ণ উৎস। MRA-এর সরকারি সাইটে Microfinance in Bangladesh (Annual Statistics), 2024 প্রকাশনাটি জানুয়ারি ২০২৫ সময়কালে তালিকাভুক্ত করা হয়েছে।
এসব পরিসংখ্যানের মাধ্যমে ক্ষুদ্রঋণ খাতের প্রতিষ্ঠান, কার্যক্রম এবং বিভিন্ন আর্থিক সূচক সম্পর্কে গবেষণাভিত্তিক ধারণা পাওয়া যায়।
ক্ষুদ্রঋণ গ্রাহকদের জন্য গুরুত্বপূর্ণ সতর্কতা
ক্ষুদ্রঋণ নেওয়ার আগে শুধু ঋণের পরিমাণ বা কিস্তির অঙ্ক দেখলেই হবে না। একজন সম্ভাব্য গ্রাহকের উচিত প্রতিষ্ঠানের পরিচয়, সনদ, ঋণের শর্ত এবং মোট পরিশোধযোগ্য অর্থ সম্পর্কে পরিষ্কার ধারণা নেওয়া।
ঋণ নেওয়ার আগে সাধারণভাবে যেসব বিষয় যাচাই করা যেতে পারে:
- প্রতিষ্ঠানটি MRA-এর সনদপ্রাপ্ত কি না
- ঋণের মোট পরিমাণ
- কিস্তির সংখ্যা
- কিস্তির সময়সূচি
- প্রযোজ্য সার্ভিস চার্জ বা অন্যান্য বৈধ খরচ
- মোট কত টাকা ফেরত দিতে হবে
- ঋণের শর্তাবলি
- অভিযোগ বা যোগাযোগের ব্যবস্থা
বর্তমান নিয়ম ও প্রতিষ্ঠানের নির্দিষ্ট শর্ত পরিবর্তিত হতে পারে। তাই সিদ্ধান্ত নেওয়ার আগে সংশ্লিষ্ট প্রতিষ্ঠানের সর্বশেষ নথি ও MRA-এর সরকারি তথ্য যাচাই করা উচিত।
MRA-এর চাকরি ও ক্যারিয়ার
সরকারি প্রতিষ্ঠানে চাকরি খুঁজছেন এমন প্রার্থীদের কাছেও MRA একটি গুরুত্বপূর্ণ প্রতিষ্ঠান হতে পারে। বিভিন্ন সময়ে সরকারি নিয়োগ বিজ্ঞপ্তির মাধ্যমে বিভিন্ন পদে জনবল নিয়োগ হতে পারে।
তবে MRA Job Circular, পদের সংখ্যা, শিক্ষাগত যোগ্যতা, বয়সসীমা, আবেদন ফি, আবেদন পদ্ধতি ও শেষ তারিখ সময়ের সঙ্গে পরিবর্তিত হয়। তাই চাকরির জন্য আবেদন করার ক্ষেত্রে MRA-এর সর্বশেষ অফিসিয়াল নিয়োগ বিজ্ঞপ্তি অনুসরণ করা উচিত।
কোনো পুরোনো চাকরির বিজ্ঞপ্তিকে বর্তমান নিয়োগ হিসেবে প্রচার করা উচিত নয়।
MRA-এর ওয়েবসাইটে কী ধরনের তথ্য পাওয়া যায়?
MRA-এর সরকারি ওয়েবসাইটে বিভিন্ন ধরনের তথ্য ও নথি পাওয়া যায়। যেমন:
- আইন
- বিধিমালা
- নির্দেশিকা
- বার্ষিক প্রতিবেদন
- মাইক্রোফাইন্যান্স পরিসংখ্যান
- সনদপ্রাপ্ত প্রতিষ্ঠানের তালিকা
- সনদ বাতিল প্রতিষ্ঠানের তথ্য
- বিভিন্ন সরকারি প্রতিবেদন
- বার্ষিক কর্মসম্পাদন সংক্রান্ত তথ্য
- নোটিশ ও প্রজ্ঞাপন
MRA-এর সরকারি ওয়েবসাইটের তথ্য নিয়মিত পরিবর্তিত হতে পারে। তাই গুরুত্বপূর্ণ কোনো সিদ্ধান্ত নেওয়ার আগে সর্বশেষ প্রকাশনা যাচাই করা উচিত।
MRA সম্পর্কিত সাধারণ প্রশ্ন ও উত্তর
MRA-এর পূর্ণরূপ কী?
MRA-এর পূর্ণরূপ হলো Microcredit Regulatory Authority।
MRA কী?
MRA হলো বাংলাদেশের ক্ষুদ্রঋণ খাতের একটি নিয়ন্ত্রক কর্তৃপক্ষ, যা আইনগত কাঠামোর অধীনে বেসরকারি ক্ষুদ্রঋণ প্রতিষ্ঠানগুলোর কার্যক্রমের ওপর নিয়ন্ত্রক ভূমিকা পালন করে।
MRA আইন কত সালের?
মাইক্রোক্রেডিট রেগুলেটরী অথরিটি আইন, ২০০৬ হলো MRA-এর মূল আইন। এটি ২০০৬ সালের ৩২ নম্বর আইন।
MRA কেন প্রতিষ্ঠা করা হয়েছিল?
বেসরকারি ক্ষুদ্রঋণ প্রতিষ্ঠানগুলোকে নিয়ন্ত্রণ কাঠামোর মধ্যে আনা এবং ক্ষুদ্রঋণ খাতে স্বচ্ছতা ও জবাবদিহিতা নিশ্চিত করার উদ্দেশ্যে MRA প্রতিষ্ঠা করা হয়।
MRA-এর সনদপ্রাপ্ত প্রতিষ্ঠান কীভাবে যাচাই করা যায়?
MRA-এর সরকারি ওয়েবসাইটে প্রকাশিত সর্বশেষ সনদপ্রাপ্ত ক্ষুদ্রঋণ প্রতিষ্ঠানের তালিকা যাচাই করা যেতে পারে।
MRA কি বার্ষিক প্রতিবেদন প্রকাশ করে?
হ্যাঁ। MRA-এর সরকারি ওয়েবসাইটে বিভিন্ন বছরের বার্ষিক প্রতিবেদন প্রকাশিত হয়েছে। ২০২৪ সালের বার্ষিক প্রতিবেদনও সরকারি সাইটে তালিকাভুক্ত রয়েছে।
উপসংহার
মাইক্রোক্রেডিট রেগুলেটরী অথরিটি বা MRA বাংলাদেশের ক্ষুদ্রঋণ খাতের একটি গুরুত্বপূর্ণ নিয়ন্ত্রক প্রতিষ্ঠান। ২০০৬ সালের আইনি কাঠামোর মাধ্যমে প্রতিষ্ঠিত এই কর্তৃপক্ষের কার্যক্রমের মধ্যে ক্ষুদ্রঋণ খাতের নিয়ন্ত্রণ, সনদপ্রাপ্ত প্রতিষ্ঠানের তথ্য, পরিসংখ্যান, প্রতিবেদন এবং সংশ্লিষ্ট বিধিমালা বাস্তবায়নের বিষয়গুলো গুরুত্বপূর্ণ।
ক্ষুদ্রঋণ গ্রহণকারী, ক্ষুদ্রঋণ প্রতিষ্ঠান, গবেষক, চাকরিপ্রার্থী এবং সাধারণ পাঠকের জন্য MRA-এর সরকারি ওয়েবসাইট একটি গুরুত্বপূর্ণ তথ্যের উৎস। বিশেষ করে কোনো প্রতিষ্ঠান বা ঋণসংক্রান্ত সিদ্ধান্ত নেওয়ার আগে সর্বশেষ সরকারি তথ্য যাচাই করা নিরাপদ ও তথ্যভিত্তিক পদ্ধতি।

